Compass Group Results Preview: Growth in Focus
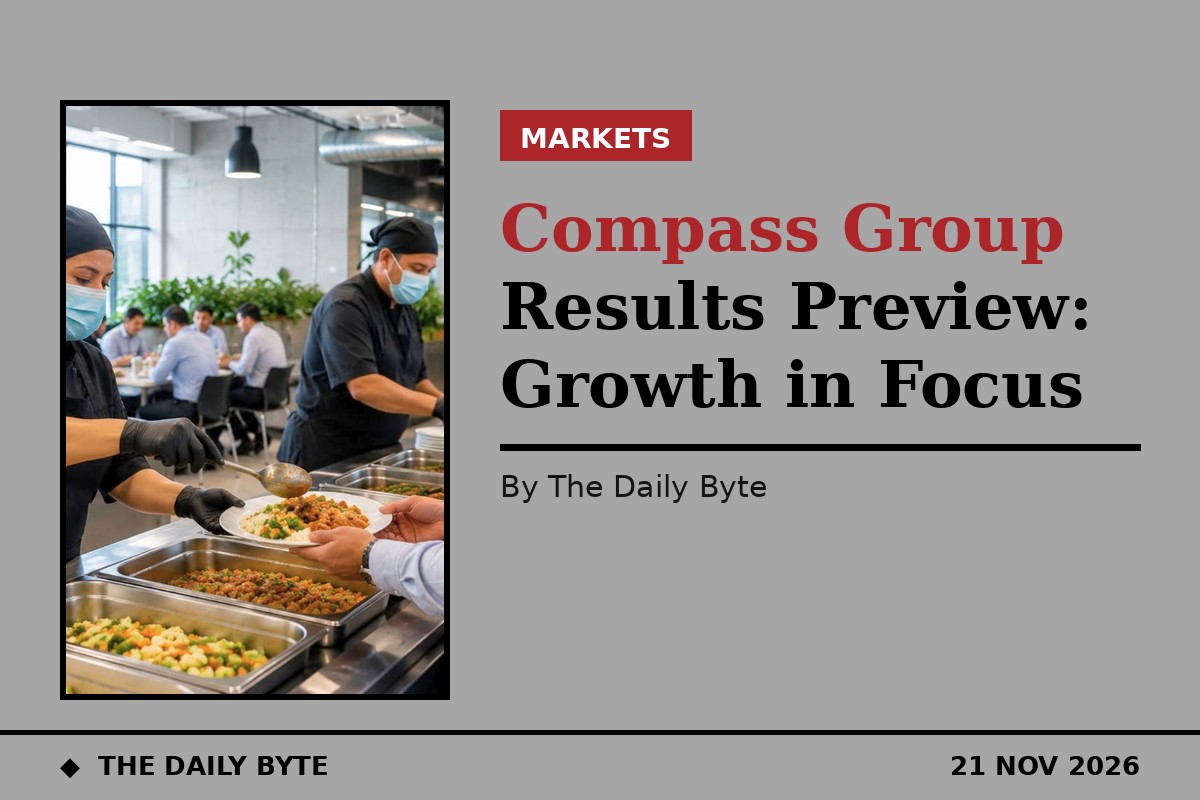
Compass Group, the world's largest contract caterer, reports full-year results on Tuesday 24 November, covering the 12 months to September 2026. Investors will be watching whether the group can deliver the growth it has guided to, after a year in which its shares have gone nowhere despite a strong trading performance.
Company-compiled consensus expects revenue of 50.7 billion dollars, organic revenue growth of 7.2 percent and operating profit of 3,743 million dollars, with underlying growth of 11.2 percent. For the following year, consensus points to revenue of 54.4 billion dollars, organic growth of 6.9 percent and operating profit of 4,067 million dollars.
Guidance reaffirmed through the year
Compass reaffirmed its outlook for fiscal 2026 at its third-quarter trading update, expecting underlying operating profit growth of more than 11 percent in constant currency. That growth is expected to come from around 7 percent organic revenue growth and roughly 2 percent from acquisitions, alongside continued margin progression. Banking group UBS has forecast full-year organic revenue growth of 7.8 percent and views consensus expectations as too low.
In the quarter ended 30 June 2026, Compass delivered organic revenue growth of 7.1 percent, with year-to-date organic growth at 7.2 percent. North America grew 7.5 percent in the quarter and 7.3 percent year to date, while international organic growth was 6.4 percent in the quarter and 6.9 percent year to date. Like-for-like growth softened in international markets because of reduced inflation and the timing of the sports and leisure calendar.
New business wins at a record pace
Annual new business wins reached 4.3 billion dollars in the 12 months to June, up 16 percent year on year, with about half coming from first-time outsourcing clients. Client retention was 96 percent, and net new business growth met the group's 4 percent to 5 percent target for the fifth consecutive year. Management described its pipeline of opportunities as the best it has ever seen and highlighted the University of Kentucky as its largest education contract to date.
Business and industry are the main drivers, typically delivering double-digit growth, and datacentres have opened up a new market, with Compass providing services during both the construction and operational phases. Sports and leisure is another important source of business, with sales outside North America growing strongly. Healthcare and senior living also offers significant long-term potential: in North America, six of the firm's biggest wins were in the sector.
Last year's results set the bar
The results will be measured against a strong previous year. In the fiscal year to 30 September 2025, revenues totalled 46.1 billion dollars, up 9.7 percent on a statutory basis and 8.7 percent higher on an organic basis, with North American organic sales up 9.1 percent and international organic sales up 7.7 percent. Underlying operating profit rose 11.7 percent at constant currencies to 3.34 billion dollars, helped by a slight improvement in underlying operating margins to 7.2 percent from 7.1 percent.
Free cash flow gained 13.5 percent to 1.98 billion dollars, while the company declared a final dividend of 43.3 cents, taking the full-year payout to 65.9 cents, up 10.2 percent year on year. Chief executive Dominic Blakemore said at the time: "2025 was another strong year for Compass, delivering underlying operating profit growth of nearly 12 percent on a constant-currency basis, with both regions performing well."
Net merger and acquisition expenditure was 2.4 billion dollars year to date at the third-quarter stage, and capital expenditure was around 3.5 percent of sales, expected to rise slightly for the full year because of client mobilisations. If current exchange rates persist, the company noted a possible currency benefit of 438 million dollars to revenue and 23 million dollars to operating profit. The risks to watch are office attendance, food inflation and the upfront cost of mobilising new contracts. This article reports market expectations only and is not investment advice.