Novartis Trims Growth Target to 5% Through 2031
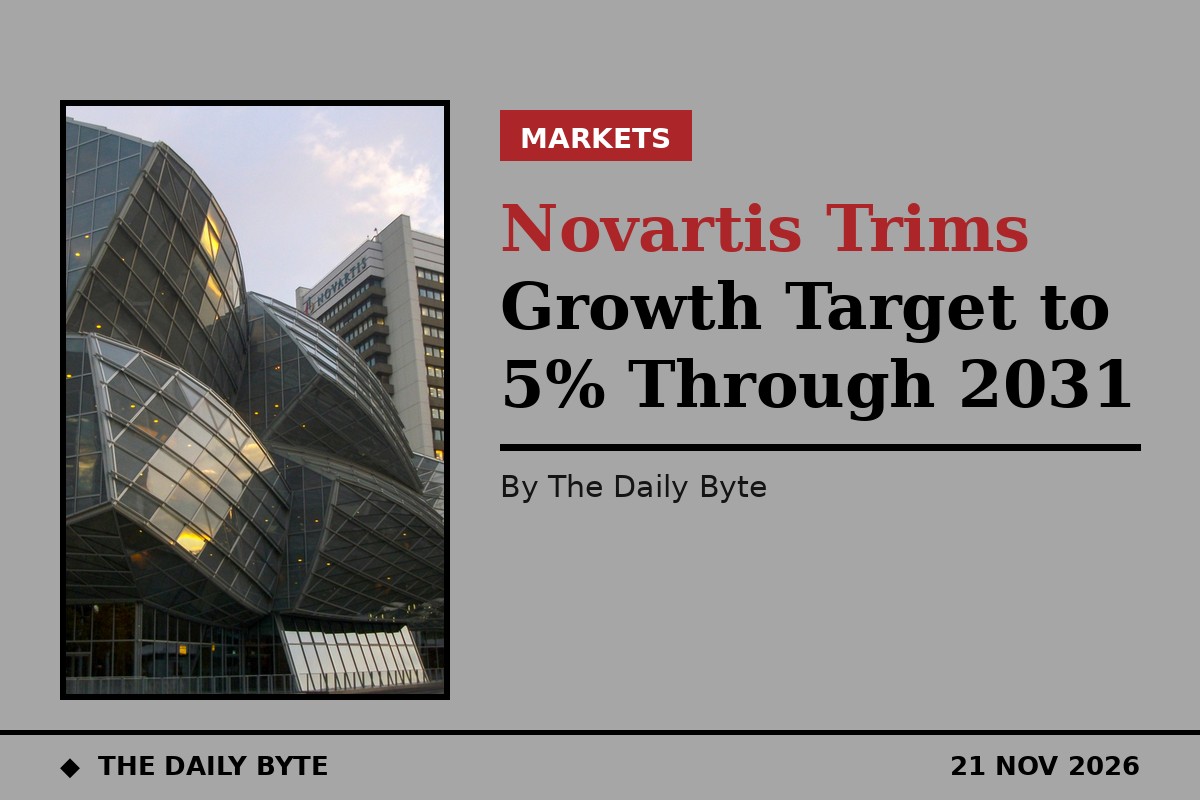
Swiss drugmaker Novartis has cut its medium-term sales growth target to 5 per cent a year through 2031, the bottom of its previous guidance range, as looming patent expiries and a run of late-stage trial failures weigh on its biggest medicines. The new target, announced at the company's annual investor event in London on Thursday, covers net sales growth at constant currencies from 2026 to 2031. Shares in Novartis fell 2 per cent in early trading after the announcement.
The revised goal replaces a range of 5 to 6 per cent annual growth set last year for 2025 to 2030. Analysts had expected sales to grow by about 4.5 per cent a year over the 2026 to 2031 period, close to the company's new figure, but the decision to pitch the target at the low end of the old range disappointed investors who had hoped for a more ambitious outlook.
The patent cliff behind the cut
The central problem is the loss of exclusivity on the drugs that drive Novartis today. Breast cancer treatment Kisqali and autoimmune drug Cosentyx, two of its best-selling medicines, will face competition from cheaper rivals by 2031, with Kisqali set to lose its United States market exclusivity in the second half of that year. Together, the two drugs are expected to bring in combined sales of 14 billion dollars in 2031, down from 16.6 billion dollars in 2030, according to Visible Alpha estimates.
Heart drug Entresto, another major earner, is already facing tough generic competition and is set to lose 4 billion dollars in sales this year. Looking further ahead, the scale of the challenge is stark: Kisqali, Cosentyx and multiple sclerosis drug Kesimpta are projected to fall from combined sales of 23.9 billion dollars in 2030 to just 7.2 billion dollars in 2035, a hole of 16.7 billion dollars, with Kisqali alone expected to drop from 11 billion dollars to 2.9 billion dollars.
Trial setbacks and a 2.2 billion dollar writedown
Novartis is also trying to rebuild confidence after several late-stage clinical study failures this year, which led to a 2.2 billion dollar writedown in the third quarter. Among the setbacks was the failure of del-desiran, a muscle weakness therapy that Novartis acquired as part of its 12 billion dollar purchase of Avidity, a deal that has drawn close investor scrutiny of chief executive Vas Narasimhan's dealmaking strategy.
Narasimhan told investors that the company's mid-term targets did not assume any large acquisitions, and that most growth beyond 2031 would come from medicines developed inside the company. In the last decade, Novartis has spent more than 100 billion dollars developing medicines internally and 63 billion dollars on business development, including acquisitions.
The offset: higher peak sales for newer drugs
The company sought to balance the lower growth target with stronger forecasts for the drugs it expects to carry sales through the 2030s. It forecast peak sales of 10 billion dollars for Kisqali, and raised its peak sales forecast for Kesimpta to 8 billion dollars from 6 billion dollars, and for leukaemia drug Scemblix and cholesterol treatment Leqvio to 5 billion dollars each from 4 billion dollars. It also raised the peak sales target for anti-inflammatory drug Rhapsido to above 8 billion dollars.
Analysts were measured in their response. Urban Fritsche of Zuercher Kantonalbank described the long-term guidance of sustained mid-single-digit sales growth as fair and decent, but said it would be a show-me story, with the pipeline having to deliver strong clinical data to convince sceptics. Consensus forecasts still show growth slowing after 2030 as the patent cliff deepens.
What to watch next
For Novartis, the next test is clinical rather than financial. The company must show that its pipeline can replace the billions in sales that will disappear as Kisqali, Cosentyx and Entresto lose protection, without resorting to the kind of large acquisition that investors have questioned. The 5 per cent target is achievable on paper, but only if the newer drugs meet their raised forecasts and the trial failures of 2026 do not repeat. Until the data arrives, the shares are likely to remain under pressure from investors who wanted a bolder plan.