Supreme Court rules ScottishPower's £28m regulator payments not tax deductible
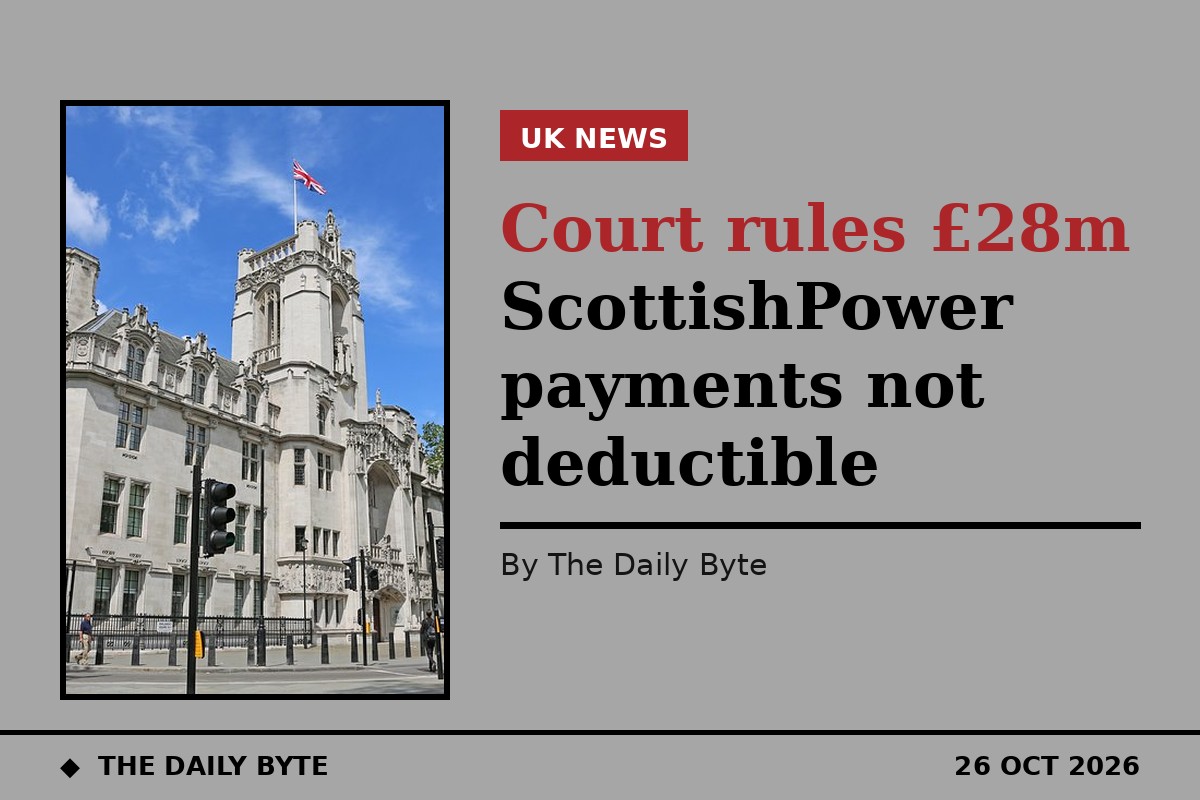
The UK Supreme Court has ruled that around £28 million paid by ScottishPower under settlements with the energy regulator cannot be deducted when calculating its taxable profits. The unanimous judgment, handed down on 21 October 2026, allowed an appeal by HM Revenue and Customs and restored an earlier Upper Tribunal decision.
The case, ScottishPower (SCPL) Ltd and others v HMRC [2026] UKSC 35, concerned payments made to customers and charities following four investigations by the Gas and Electricity Markets Authority, whose work is carried out by Ofgem. The investigations found serious breaches of the conditions governing gas and electricity supply and of energy-saving requirements.
Penalties in all but name
The authority had initially intended to impose substantial penalties. Instead, settlements were reached under which ScottishPower made the payments while only nominal penalties of £1 were imposed. It was agreed that an actual £28 million fine would not have been deductible, but ScottishPower argued that the redress payments were different and therefore deductible.
Lady Rose and Lord Doherty gave the judgment, with which Lord Reed, Lord Stephens and Lady Simler agreed. The court held that the payments were sufficiently akin to penalties that they were not expenditure incurred for the purposes of ScottishPower's trade, and that they were not voluntary because they were paid to avoid larger penalties.
Wider significance
The ruling matters well beyond one company. Regulated businesses that agree settlements involving payments to customers or charities, rather than formal fines, will now need to treat those sums as post-tax costs when negotiating with regulators, since the court has made clear that the form of a payment does not by itself decide its tax treatment.
Sources: UK Supreme Court judgment UKSC 35; Bloomberg Tax.