CAC 40 Leads Europe With 2% Weekly Gain Despite Sell-Off
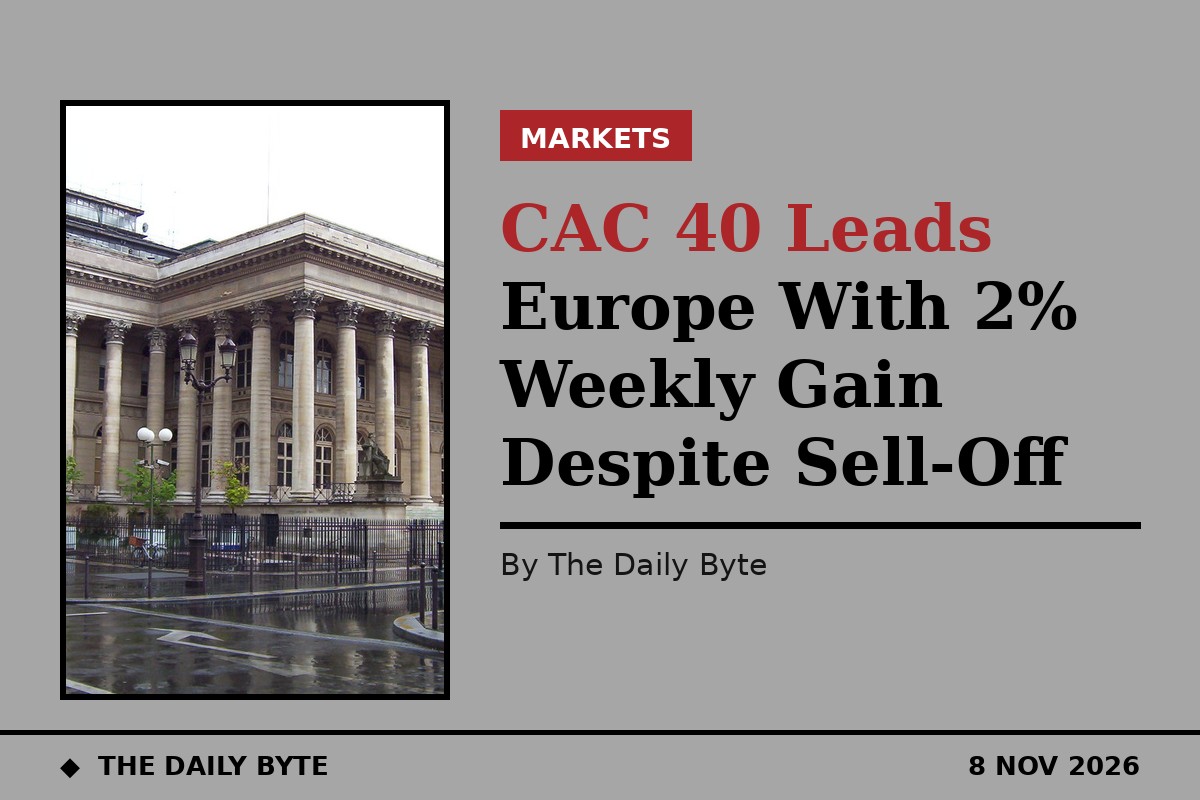
France's CAC 40 index led Europe's major stock markets over the past week, rising 2.13% even though a global sell-off in technology shares dragged Paris lower on Friday.
The Paris benchmark was the strongest performer among the region's big indices. Germany's DAX ended the week flat, Italy's FTSE MIB climbed 1.12%, and London's FTSE 100 fell 0.52%, according to T. Rowe Price's weekly markets update.
The weekly gain came despite a difficult end to the week. European stock markets fell sharply on Friday as heavy selling in technology shares followed a substantial overnight decline on Wall Street, where the Nasdaq Composite entered correction territory after falling 5.52% on Thursday, its largest single-session loss in 19 months.
On Friday, the pan-European STOXX 600 fell as much as 1.6%, marking its steepest daily decline since July. Germany's DAX declined 1.7%, France's CAC 40 lost 1.4%, Spain's IBEX 35 fell 1%, and London's FTSE 100 retreated 1.5%.
European markets nevertheless escaped the worst of the rout. With less exposure to artificial intelligence and technology stocks than the United States, the region's indices generally avoided the steeper declines seen on Wall Street. European banks were among the beneficiaries during the week, while defence shares fell.
The technology sell-off was driven by a reassessment of the huge capital spending planned for artificial intelligence infrastructure and whether those investments will ultimately generate adequate returns. Concerns about tighter oversight of the AI industry after the US midterm elections, in which Democrats gained control of both chambers of Congress, added to the pressure, along with disappointing outlooks from major semiconductor companies.
Paris held on to its weekly gain even though the French economy itself showed signs of strain. The final October composite purchasing managers' index for the eurozone fell to 51.7 from 53.1, with France dropping sharply into contraction at 46.6, while Germany remained relatively strong at 53.4 and Spain at 56.2.
Eurozone inflation also accelerated. October headline inflation rose to 4.0% from 3.8% the previous month, the fastest pace since September 2023 and double the European Central Bank's 2% target. The rise was largely energy-driven, with energy inflation reaching 20.8%.
Oil prices, by contrast, fell over the week as markets priced in a lower probability of near-term escalation with Iran and signs of renewed diplomatic activity. Brent crude dropped below $100 a barrel during the week. Lower oil prices reduced inflation expectations, supported bonds, and benefited travel and consumer-sensitive sectors, while energy shares came under pressure.
Despite Friday's losses, European equities continued to outperform their US counterparts over 2026 as a whole, with the STOXX 600 holding a year-to-date gain of more than 10%, compared with just over 7% for the S&P 500.
Investors will now watch whether the technology sell-off proves to be a temporary adjustment in valuations or signals a more lasting change in expectations for AI investment, with the next US inflation data and the ongoing European earnings season likely to set the tone for the coming week.