CoreWeave Plans $4bn Loan to Cut Costly Debt Burden
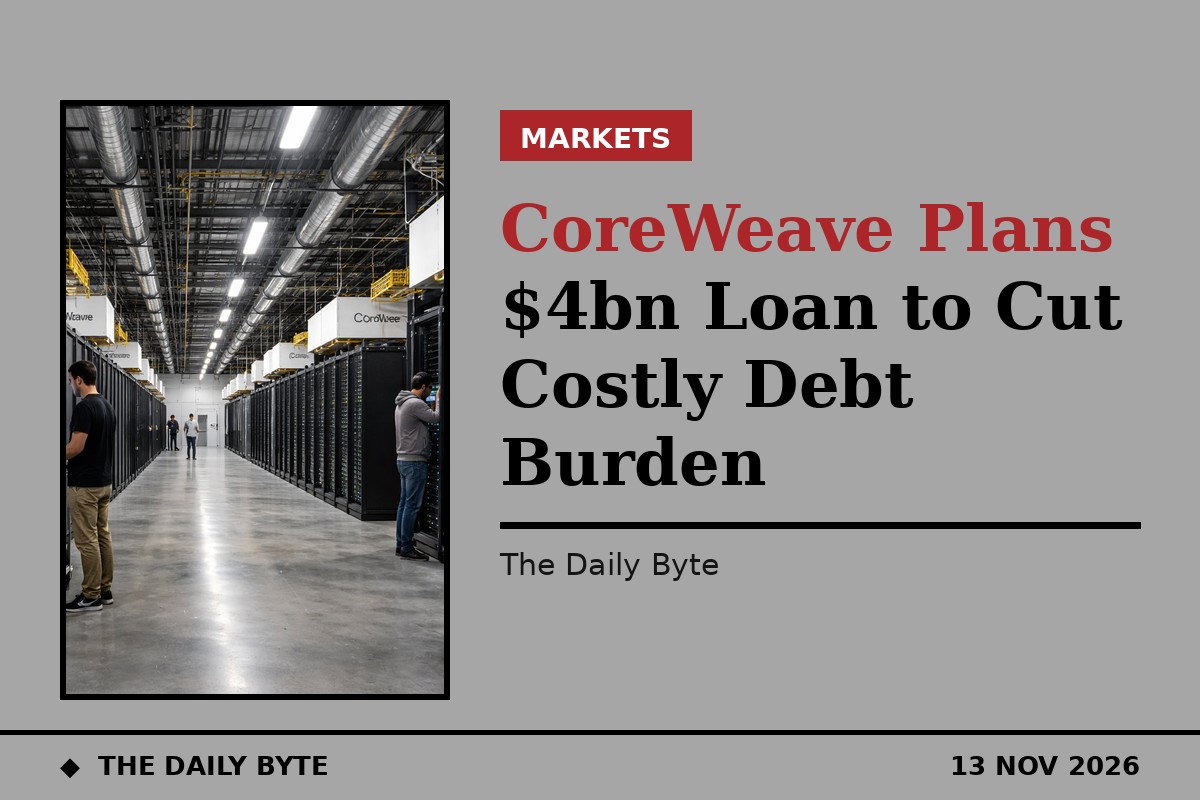
CoreWeave is reportedly preparing to raise at least $4 billion through an investment-grade loan, as the artificial intelligence cloud provider looks for cheaper ways to fund its rapid expansion. Bloomberg reported the plan, citing people familiar with the matter, and the report was carried by Stocktwits and other outlets on 11 November.
Morgan Stanley and Mitsubishi UFJ Financial Group are leading the potential financing, according to the report. The loan could come to market as soon as next week, although the plans have not been finalised and the terms could still change.
The financing would be backed by computer chips and related customer contracts, the same structure CoreWeave used for an $8.5 billion investment-grade facility raised in March. That earlier deal carried lower rates because it was supported by contracts with Meta Platforms.
Cheaper borrowing is the point
The new loan matters because CoreWeave’s borrowing costs have become a central concern for investors. Early discussions point to a yield of between 7% and 7.5% on the new facility, according to the Bloomberg report. That is roughly half the yield of about 15% recently demanded on the company’s existing unsecured bonds.
On a $4 billion loan, a gap of that size would represent roughly $300 million a year in lower interest costs, according to analysis published by GuruFocus on TradingView, although the final saving would depend on the pricing and structure agreed.
CoreWeave’s chief executive, Michael Intrator, told investors on the company’s earnings call on 10 November that it would not use the unsecured debt market to fund the business at current yields, and that it did not need to. He also said the company had secured about $9 billion in customer prepayments and deposits, which he described as its cheapest source of capital.
Strong sales, heavy losses
The loan plan followed a strong set of third-quarter results. CoreWeave reported revenue of $3.66 billion for the three months to 30 September, up 168% on a year earlier, and raised its full-year 2026 revenue forecast to between $13 billion and $13.3 billion. Its contracted revenue backlog stood at about $132.5 billion at the end of the quarter, up from about $104.2 billion at the end of June.
Growth, however, remains expensive. Interest expenses reached $846 million in the quarter, contributing to a net loss of $709 million. Management expects capital expenditure of between $37 billion and $39 billion for 2026, reflecting the scale of data-centre building needed to meet customer demand. Fourth-quarter interest expenses are projected at between $1.05 billion and $1.15 billion.
The company rents computing capacity powered by Nvidia graphics processors to AI developers and large technology firms. Nvidia is both its main chip supplier and a major investor, which ties CoreWeave’s fortunes closely to the wider AI hardware market.
Shares swing after the news
CoreWeave’s shares closed the regular session on 11 November up 24.71% at $60.77 after the earnings beat, before falling about 5% in after-hours trading as reports emerged about Nvidia’s chief executive, Jensen Huang, and the turmoil at the chipmaker. The stock has fallen 15% so far this year, according to Stocktwits.
Intrator also told CNBC that he had cancelled his pre-arranged plans to sell company shares, limiting any future sales to restricted stock units needed for routine tax obligations. He said the data-centre buildout was not being delayed or affected by the recent United States mid-term election results.
Whether the loan goes ahead on the terms reported will be a test of investor appetite for AI infrastructure debt. Cheaper financing would help CoreWeave keep building, but the final pricing, collateral and repayment terms will decide how much relief it actually provides.
Sources: Stocktwits, reporting Bloomberg, and TradingView / GuruFocus.