K+S Shares Slip 5% as Q3 Costs Weigh on Profits
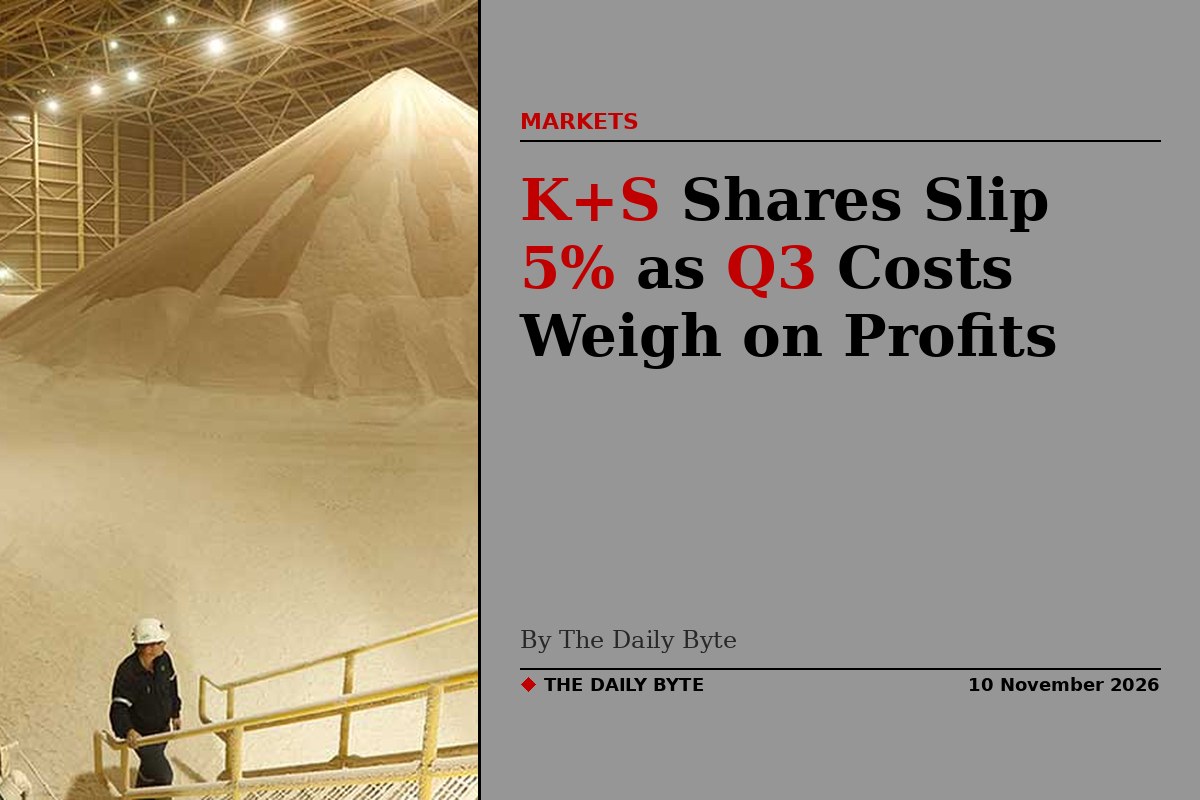
Shares in German potash and salt miner K+S fell about 5% on Tuesday, 10 November 2026, after third-quarter results showed higher revenue but lower profits, as rising logistics and energy costs ate into earnings. The stock traded at 12.77 euros at 17:15 CET, down 4.99% from Monday's Xetra close of 13.44 euros.
Third-quarter revenue rose to 933.9 million euros from 879.1 million euros a year earlier, the company said. Earnings before interest, tax, depreciation and amortisation (EBITDA) slipped to 107.6 million euros from 110.7 million euros, although that was ahead of the Vara consensus estimate of 102.2 million euros. The company said the figures were broadly in line with market expectations.
Costs offset stronger sales
Both customer segments contributed to the revenue growth. Agriculture revenue increased to 642 million euros, with the average selling price excluding trade goods rising to 355.60 euros per tonne, although sales volumes of 1.61 million tonnes were moderately below last year's 1.74 million tonnes. The Industry+ segment, which includes de-icing salt and industrial products, saw revenue climb to 292 million euros.
Higher logistics and energy costs, together with a scheduled maintenance break at the Bethune plant in Canada, offset the revenue gains in the quarter. The first nine months of the year presented a stronger picture, with EBITDA rising to 562.7 million euros from 421.0 million euros a year earlier and adjusted free cash flow reaching 119.3 million euros, up from 61.6 million euros.
Outlook narrowed with higher midpoint
K+S narrowed its full-year 2026 EBITDA outlook to between 700 million and 750 million euros, from a previous range of 680 million to 760 million euros. The midpoint therefore rises to 725 million euros from 720 million euros. Management raised the lower end because global potash supply constraints make a weaker demand scenario less likely, while the upper end was cut because an expected overseas price increase has not materialised.
The company kept capital expenditure guidance at 580 million to 600 million euros and still expects adjusted free cash flow in the positive mid- to high-double-digit million-euro range. De-icing salt volumes are now expected to reach at least 2.7 million tonnes in 2026, up from at least 2.6 million tonnes previously. Strategic projects remain on track, including the Werra 2060 transformation and the Bethune ramp-up, and the regulatory process for the Qemetica salt-business acquisition continues, with closing still expected in the first quarter of 2027.
ad-hoc-news: K+S stock slips as costs weigh despite higher EBITDA midpoint