FTSE MIB Jumps 2.7% as Milan Banks Lead Rally
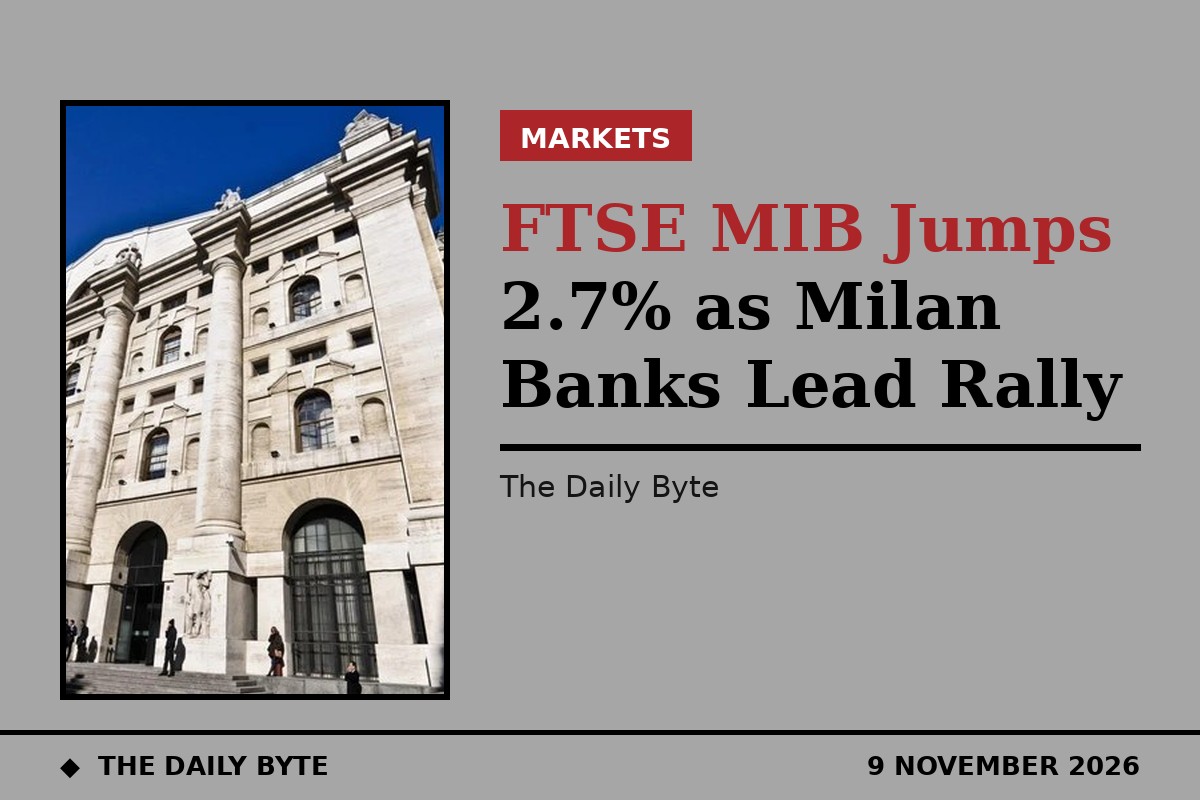
Milan's FTSE MIB led a broad European stock market rebound on Monday, 9 November 2026, closing 2.69% higher at 51,399.88 as banking shares surged on merger news and falling oil prices lifted sentiment across the region.
All nine major European indices closed higher on the day. The Euro Stoxx 50 added 1.94% to 6,290.45, Germany's DAX rose 1.73% to 26,267.19 on the Xetra close, and Spain's IBEX 35 gained 1.93%. The pan-European Stoxx 600 finished 1.26% higher at 656.52, France's CAC 40 rose 1.16% to 8,233.30, and London's FTSE 100 closed 1.02% higher at 10,782.87.
Banco BPM surges on Credit Agricole proposal
Banco BPM was the standout performer in Milan, jumping 10.7% after Crédit Agricole proposed an amicable combination of its Italian banking operations with the listed lender. The deal would create Italy's third-largest bank, and investors welcomed the prospect of further consolidation in the Italian banking sector.
UniCredit rose 5.8% after reporting record results for the first nine months of the year. The bank also said it should receive the remaining regulatory approvals to combine its German operations with Commerzbank in the coming months, earlier than initially expected. Intesa Sanpaolo added 2% after Italy's market regulator approved the document for its takeover offer for Monte dei Paschi di Siena.
Banks and miners lead the sectors
Banks were among the strongest sectors across Europe, rising 2.78%, while basic resources climbed 3.14%, the best of the eight Stoxx Europe 600 sectors. Technology shares also recovered, gaining 2.00%, with semiconductor stocks among the beneficiaries: ASML rose 4.7%, ASM International added 3.4% and Soitec gained 5.9%.
Oil and gas was the exception, falling for a seventh straight session as Brent crude slid by around 5% to about $93 a barrel. Brent had traded above $112 at the start of the month, and the sharp drop eased worries that energy costs would keep inflation elevated for longer.
Rebound after two days of losses
The rally came after two days in the red. The Stoxx 600 almost erased a 1.4% sell-off over the previous two sessions as traders reassessed the implications of a political shift in Washington and a recovery in technology shares.
The next test comes quickly. Investors are watching US inflation data due on Tuesday, 10 November, which will shape expectations for the Federal Reserve's December meeting, alongside forthcoming euro-area inflation and growth figures. This article is for information only and is not investment advice.