Oil prices set for second weekly fall as Brent holds $95
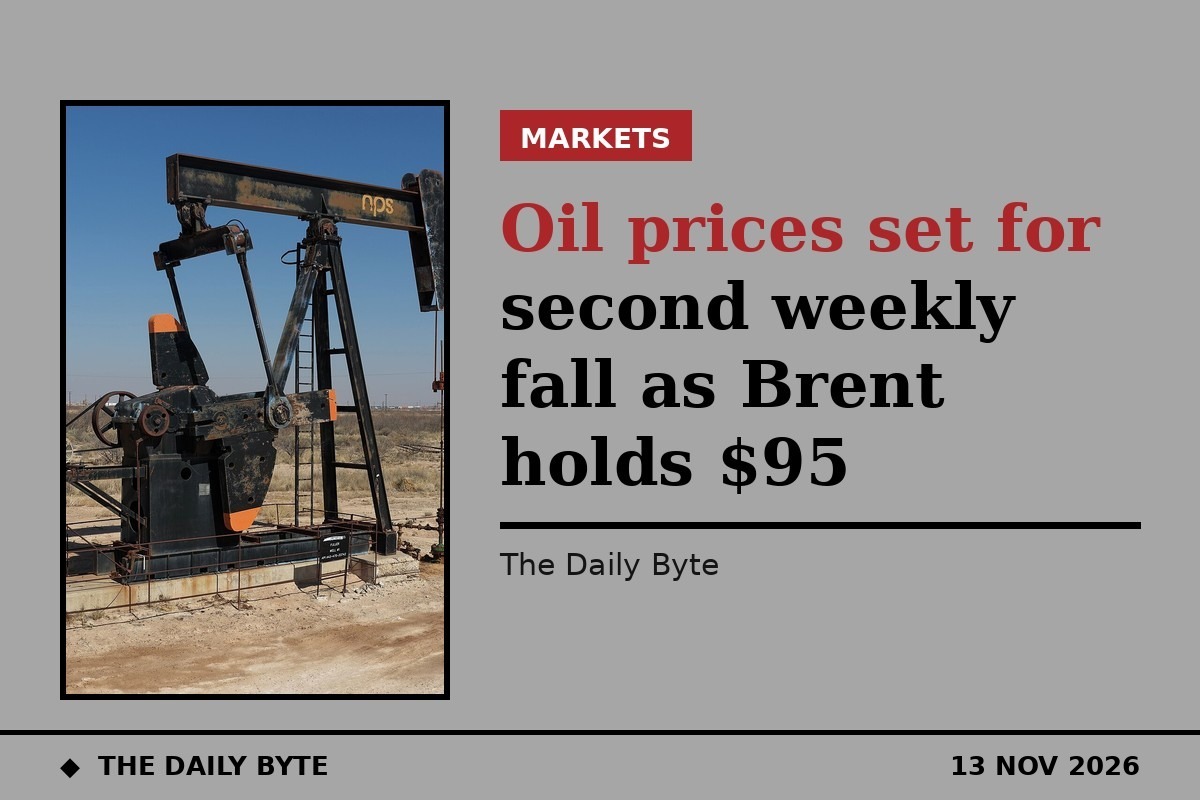
Oil prices were mixed in early trading on Friday 13 November, but remained on course for a second consecutive weekly fall, as traders weighed the continuation of a United States blockade of Iran against the danger of further attacks on shipping in the Gulf.
Brent crude futures were little changed at $95.41 a barrel at 0242 GMT, down one cent on the day, while the United States benchmark West Texas Intermediate (WTI) fell 20 cents, or 0.25%, to $88.52 a barrel.
Despite the steadier tone on Friday, Brent was set for a fall of 2.4% over the week, after plunging 16% the previous week. WTI was set for a weekly decline of 2.5%, after dropping 13% the week before, in a market that has swung sharply with each new development in the Middle East.
Blockade lowers fears of a wider war
The United States plans to continue its Iranian blockade, a step that traders read as reducing the chance of renewed large-scale fighting that could disrupt Middle East supplies. That judgement has taken some of the risk premium out of the price, even though the underlying confrontation has not ended.
President Donald Trump has said that a deal with Iran was not necessary to end the war, a position that has left markets judging the blockade, rather than a negotiated settlement, as the more likely course in the near term. With no agreement in sight, traders have focused instead on whether supplies can keep moving through the region.
Brent and WTI had jumped in the previous session after attacks on Saudi energy infrastructure escalated and shipping disruptions through the Strait of Hormuz threatened global oil flows. A separate Reuters market report on Friday put Brent at $95.45 and WTI at $88.39 a barrel, each down more than 0.3%, confirming the softer tone after that jump.
Shipping risks have not gone away
The fall in prices does not mean the danger to supplies has passed. Attacks on shipping remain a threat, and the Strait of Hormuz carries a large share of the world's seaborne oil. Any further incident in the Gulf could push prices higher again within hours, as the market has done repeatedly in recent weeks.
That tension explains why prices have not fallen further. The blockade points one way, towards calmer supplies, while the attacks on Saudi facilities and the disruption to shipping point the other. Traders are caught between the two, which is why Brent has moved in large steps in both directions rather than settling.
What it means for UK fuel costs
For households and businesses in Britain, the direction of crude prices matters because fuel costs feed into the price of petrol and diesel, and from there into transport and heating bills. A sustained fall in crude would, over time, ease some of that pressure, although pump prices do not move in step with crude on a daily basis and other costs, including refining and distribution, also play a part.
For now, the market's message is one of caution rather than relief. Two weekly falls in a row suggest the worst of the recent spike is passing, but with the blockade in place, shipping under threat and no deal on the table, few traders are willing to call the turn. The next move is likely to depend on what happens in the Gulf, not on the trading screens in London.
Prices quoted in this article are as reported at 0242 GMT on Friday 13 November 2026. This is market reporting only, not financial advice.