What Are ACA Premium Tax Credits? Subsidies Explained
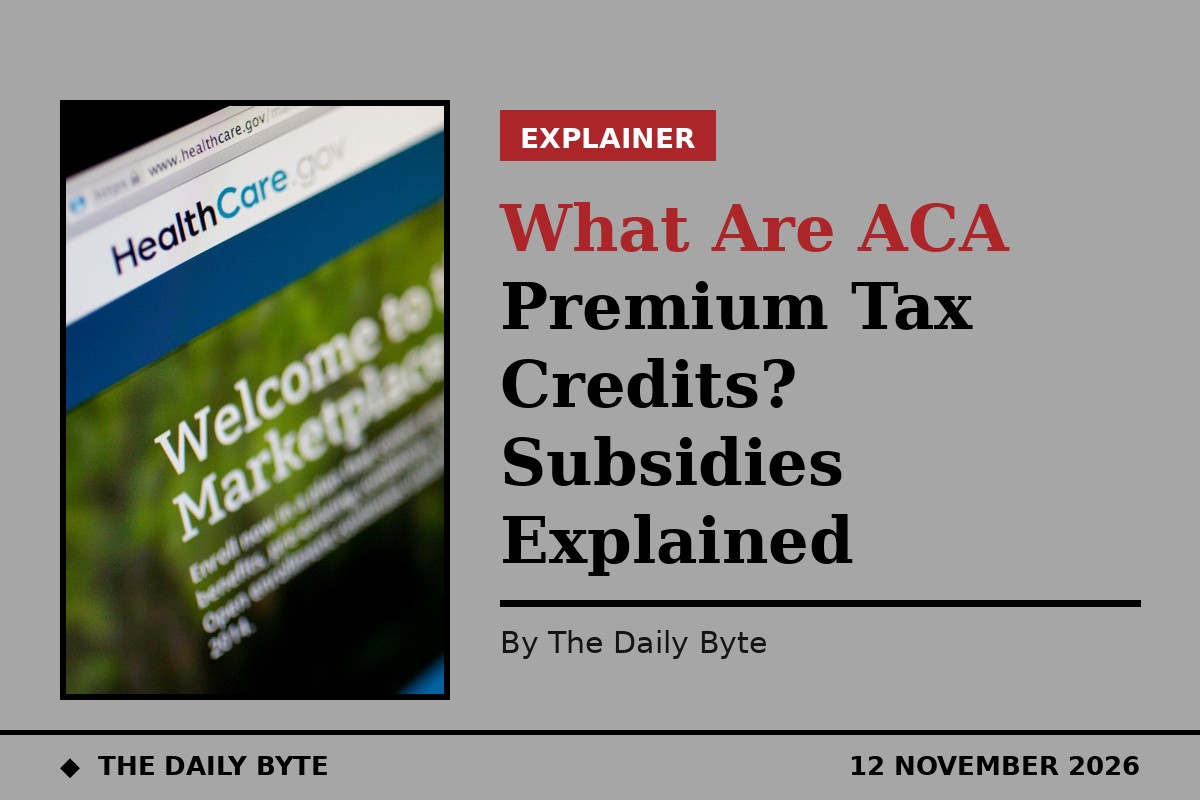
Premium tax credits under the Affordable Care Act, known as ACA premium tax credits, are government payments that lower the monthly cost of health insurance bought through the Act's marketplaces, principally HealthCare.gov. The credit is worked out from a household's income and can be paid in advance, month by month, directly to the insurer, so the person insured pays a smaller premium. The enhanced version of the credit, the more generous help at the centre of the 43-day United States government shutdown, is due to expire at the end of December 2026, and the deal that reopened the government on 11 November did not extend it.
That single fact explains why a technical-sounding tax credit dominated American politics for six weeks. About 24 million people buy insurance through the Affordable Care Act marketplaces, according to the Associated Press, and for many of them the credit is the difference between cover they can afford and cover they cannot. Democrats made extending the credits the condition of their support for government funding. The deal that ended the shutdown gave them only a promised Senate vote, not the extension itself.
What is a premium tax credit?
HealthCare.gov, the official federal marketplace website, defines a premium tax credit as a tax credit you can use to lower your monthly Marketplace plan premium. The credit is based on the household information and estimated income entered on the application. You can use all, some or none of your premium tax credit in advance to lower your monthly premium.
That advance payment is the part most people actually experience. Rather than waiting until the end of the tax year, the credit is sent to the insurer each month and the household pays the reduced premium. If the household uses more of the credit than it qualifies for, based on its final yearly income, it must pay the difference when it files its federal income tax return. If it uses less than it qualifies for, the difference counts towards its refund or lowers the amount of tax it owes. The credit can only be obtained through the Marketplace: you can buy health insurance through other sources, HealthCare.gov says, but the only way to get the premium tax credit is through the Marketplace.
Under the standard rules set out by HealthCare.gov, households with income between 100 percent and 400 percent of the federal poverty level qualify for the premium tax credit that lowers their monthly premium. The lower the income, within that range, the larger the share of the premium the credit covers. The credit lowers the monthly premium itself. It does not directly pay the other costs of using health care, such as deductibles and copayments when treatment is received.
What is the Affordable Care Act marketplace?
The Affordable Care Act, often called Obamacare, is the 2010 federal law that created the marketplaces where people can buy health insurance. HealthCare.gov is the federal marketplace, and it is where people who buy their own cover, rather than getting it through an employer, go to compare plans and apply for help with the cost.
The marketplace matters because health insurance in the United States is otherwise tied, for most working-age people, to a job. The marketplace is the alternative for people who are self-employed, work for a small employer that does not offer cover, work part-time, or are between jobs. The premium tax credit is the mechanism that makes marketplace cover affordable for lower- and middle-income households. Without it, the full monthly premium would fall on the household alone.
What does "enhanced" mean?
The credits at the centre of the current row are the enhanced premium tax credits. Congress temporarily made the credits more generous and available to more households than the standard rules provide, so that more people paid less for their cover. The Associated Press describes them as the enhanced tax credits that lower the cost of health insurance bought through the Affordable Care Act marketplaces.
That enhancement was always temporary. It is now due to end at the end of December 2026. From January, unless Congress acts, households that have been receiving the enhanced help will pay more of their premium themselves. The Associated Press reported that millions of Americans were staring down rising insurance premiums as the deadline approached, and that the argument over the credits was the central issue of the shutdown.
It is important to be clear about what expires. The shutdown deal did not repeal the Affordable Care Act, close the marketplaces, or abolish the underlying premium tax credit system described by HealthCare.gov. What is at stake is the extra, temporary help on top of the standard credit. If that extra help ends, the standard credit continues, but households pay more than they have been paying under the enhanced rules.
Why did the credits cause a government shutdown?
The shutdown began on 1 October 2026, the first day of the federal financial year, when Congress failed to pass the annual spending bills. Democrats, who were in the minority in both chambers, refused to support a funding bill that did not extend the health care subsidies. The Associated Press reported that the Democrats failed to secure their main demand during the shutdown, which was an extension of the health care subsidies that many of the 24 million people who buy insurance through the Affordable Care Act rely on to help defray costs.
The standoff lasted 43 days, the longest in American history, passing the previous record of 35 days set during the funding lapse of December 2018 to January 2019. It left about 800,000 federal workers furloughed or working without pay, disrupted food assistance for millions of families, and snarled air travel across the country. Senator Elizabeth Warren, a Democrat from Massachusetts, said during the dispute that the American people wanted Democrats to stand and fight for health care. House Democratic leader Hakeem Jeffries of New York said his party would not support spending legislation that failed to extend the Affordable Care Act tax credits.
The deadlock broke on Sunday 8 November, when the Senate voted 60 to 40 to advance a bipartisan funding deal, with eight Democrats joining most Republicans. Senate Democratic leader Chuck Schumer of New York voted against advancing the package because it failed to fully address the health care funds. The Senate then passed the package, the House approved it by 222 votes to 209 on the evening of 11 November, and President Donald Trump signed it at about 9.45pm Eastern time that night.
What did the shutdown deal actually decide?
On the credits, the deal decided almost nothing. It contains no extension of the enhanced tax credits. Instead, the package guarantees a vote on the issue in the Senate in December, which was not enough for most Democrats, who rejected the deal and voted against it. The Associated Press reported that the Senate vote is promised no later than the second week of December, and that it carries no guaranteed outcome.
The rest of the package is a funding deal, not a health care deal. Its core is a continuing resolution that funds most of the federal government at existing levels through 30 January 2027, with three full-year spending bills attached covering agriculture, veterans' affairs and military construction, and the legislative branch. It provides back pay for furloughed federal workers, reinstates workers who received layoff notices during the shutdown, and fully funds the Supplemental Nutrition Assistance Program, known as SNAP, through the end of the financial year. On health care, it postpones the argument by a few weeks.
What happens if the credits expire?
If the enhanced credits expire at the end of December and Congress does not extend them, households buying cover through the marketplaces will pay more of their premiums from January. The size of the increase depends on the household's income and the cost of plans where it lives, so there is no single figure that applies to everyone. What is certain is the direction: the help gets smaller, and the amount households pay themselves gets larger.
That is why the December vote matters. If the Senate votes to extend the credits and the House and the President agree, the enhanced help continues. If the Senate votes against an extension, or if no vote produces a law, the enhanced credits end. Some households may decide the higher premium is unaffordable and go without cover, which is the outcome Democrats warned about throughout the shutdown. Others may switch to cheaper plans with higher deductibles. Either way, the expiry would be felt first in household budgets, in January, when the new premiums fall due.
What happens next?
The next step is the Senate vote promised for no later than the second week of December. A vote alone does not change the law. For the credits to be extended, a bill must pass the Senate, pass the House of Representatives, and be signed by the President. The House has been out of session since 19 September and was recalled to vote on the funding package; whether it will support an extension of the credits is not settled.
The timing is tight. The credits expire at the end of December, only weeks after the promised vote. If Congress misses that window, the enhanced help lapses and can only be restored by later legislation, which would not undo the higher premiums already charged in January. The shutdown is over. The argument that caused it is not, and the December vote is where it will be fought next.
Frequently asked questions
Who qualifies for a premium tax credit? According to HealthCare.gov, households with income between 100 percent and 400 percent of the federal poverty level qualify for the premium tax credit that lowers the monthly premium. The credit is based on household information and estimated income entered on the application, and it is only available through the Marketplace.
Do I receive the money myself? No, not usually. The credit can be paid in advance, month by month, directly to the insurer, so you pay a lower premium. You can also choose to use some or none of it in advance and claim the rest when you file your federal income tax return. If you use more than you qualify for, based on your final yearly income, you must pay the difference back at tax time.
Is the Affordable Care Act being repealed? No. The shutdown deal did not repeal the Affordable Care Act, close the marketplaces, or abolish the premium tax credit. What is due to expire at the end of December 2026 is the enhanced, temporary version of the credit, not the law itself.
What is the difference between the standard credit and the enhanced credit? The standard premium tax credit is the long-standing help described by HealthCare.gov, based on income between 100 percent and 400 percent of the federal poverty level. The enhanced credit is a temporary, more generous version that Congress added on top of it. The shutdown was fought over extending that enhancement, not over the standard credit.
When will we know whether the credits are extended? The Senate has promised a vote no later than the second week of December 2026. That vote will show whether a majority of senators support an extension, but an extension only becomes law if the House of Representatives also passes it and the President signs it. Until then, the credits remain due to expire at the end of December.