What Happens to Metro Bank Customers If It Is Sold?
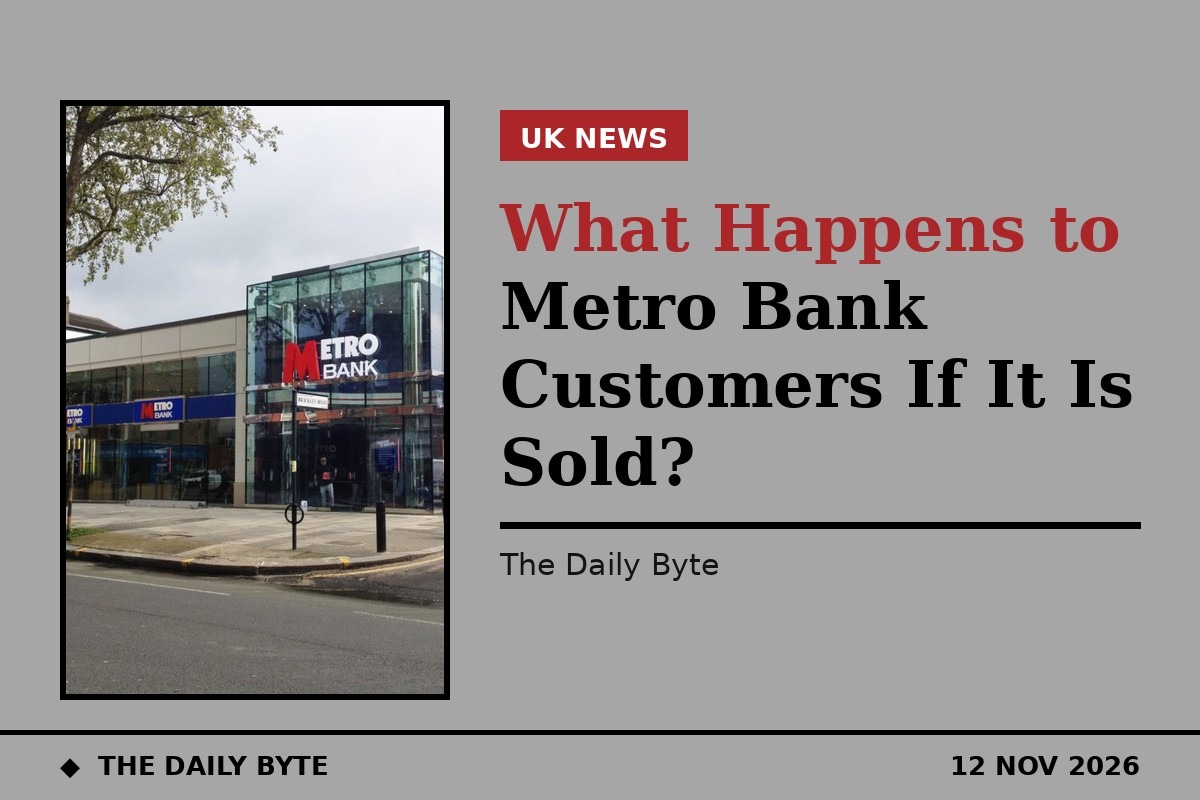
Nothing changes for Metro Bank customers for now. On Thursday 12 November 2026, Metro Bank announced it had started a formal sale process, inviting offers for the whole company, but it also said it is not in talks with any buyer, has received no approach, and there is no certainty that any offer will be made. Accounts, cards, branches and the app all continue as normal while the process runs, and the bank says it remains confident in its standalone plans.
The announcement matters because Metro Bank is a familiar name on the high street, with 78 branches and around 2.7 million customers across the United Kingdom. It was launched in 2010 as the first new high street bank in Britain for more than 150 years, and it built its reputation on long opening hours, seven-day opening in many stores and a focus on personal service. After a difficult period that included an accounting error in 2019 and heavy losses, it secured a £925 million funding package in 2023 and has spent the past three years rebuilding. Its board now says that turnaround has put it in a position to consider a sale as the next phase of growth.
This explainer answers the questions customers are asking: what a formal sale process actually is, what would happen to accounts, savings, mortgages and branches if a buyer emerged, what protection exists for deposits, and what customers should and should not do while the process is under way.
What is a formal sale process?
A formal sale process is a recognised route under the City Code on Takeovers and Mergers, the rulebook that governs takeovers of listed British companies. Metro Bank Holdings PLC is listed on the London Stock Exchange, so any bid for it must follow those rules. In its announcement, made through the regulatory news service at 7am on 12 November, the board said it was undertaking a strategic review of options for how the company builds on its strategic delivery to accelerate growth, including commencing a formal sale process.
The process is run under the supervision of the Takeover Panel, the body that enforces the code. The panel has agreed that discussions with interested parties can take place on a confidential basis, and it has granted a dispensation from parts of the code. That means a party taking part in the process does not have to be publicly named, and the usual 28-day deadline for a potential bidder to announce a firm offer or walk away does not apply while it remains in the process. Morgan Stanley has been appointed as the bank's lead financial adviser, and interested parties are invited to contact the bank through Morgan Stanley.
Before they can take part, interested parties must sign a non-disclosure agreement and a standstill agreement on terms satisfactory to the board. A standstill agreement restricts what a party can do in relation to the company's shares while talks continue. The board has reserved the right to alter or end the process, or to reject any approach, at any time. Shareholders have been advised to take no action, and no timetable has been given: the bank said further announcements would be made as appropriate, including on timing.
It is important to understand what this announcement is not. It is an announcement under Rule 2.4 of the Takeover Code, which covers a possible offer. It is not a Rule 2.7 announcement, which would be a firm offer with terms and a price. There is, at this stage, no bidder, no price and no deal. Reporting on the day said the bank was valued at about £1.2 billion and that its shares rose about 3 per cent after the announcement, but that is the stock market's reaction to the possibility of a sale, not evidence that a sale will happen.
Why is Metro Bank considering a sale now?
The board's case is that the bank has completed a substantial transformation and now has strong operating momentum. It reported the highest profits in its history for the full year 2025, and in August 2026 it reported that pre-tax profits had risen by 41 per cent to £61 million for the six months to the end of June, its most profitable half-year on record. Lending in its target areas grew, and current account balances continued to rise. The bank reaffirmed its guidance in a trading update on 4 November 2026, saying it expects a return on tangible equity of more than 13 per cent in the fourth quarter of 2026, more than 15 per cent in 2027 and more than 18 per cent in 2028.
The bank also says it has the lowest cost of deposits of any UK high street bank, alongside strong capabilities in commercial lending and a physical branch network that meets its customers' needs. In other words, the board is presenting the sale process as a choice made from a position of strength rather than distress: having fixed the business, it wants to test whether a buyer would pay more for it than it is worth on its own. That is a very different situation from the rescue of 2023, when the £925 million package was needed to stabilise the bank.
Press reporting has suggested possible interest from Pollen Street, the owner of rival lender Shawbrook, but no bidder has been named and Metro Bank has said it is not in active discussions with any potential offeror. The board is also in transition: chairman Robert Sharpe left at the end of October and a permanent replacement has yet to be found. None of that changes anything for customers in the short term.
What happens to my account if Metro Bank is sold?
If a buyer eventually emerges and a deal completes, customers would normally notice very little at first. In a takeover of a bank, the buyer acquires the company, and the bank usually continues to operate under its existing banking licence, with the same account numbers, sort codes, cards and direct debits. A new owner may eventually rebrand branches, change product names or merge systems, but that takes months and customers are written to well in advance of any change. Direct debits and standing orders are not cancelled by a change of ownership, and money in an account does not move anywhere unless the customer moves it.
The most recent example of a British bank changing hands quickly was Silicon Valley Bank UK, which was sold to HSBC for £1 over a weekend in March 2023. Its customers kept their accounts and card details and were able to use them as normal on the Monday morning. A sale of Metro Bank would be expected to follow the same pattern if it happened at all: continuity first, with any rebranding or systems change handled gradually afterwards.
What a sale does not mean is that branches close overnight or that accounts are frozen. Metro Bank has 78 branches, and its branch network is part of what the board describes as its strategic value, so a buyer would be buying that network rather than dismantling it on day one. Any future branch closures would be a commercial decision by the new owner, announced in advance, and would be subject to the usual regulatory expectations about access to banking services.
Are my savings protected?
Yes. Metro Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority, and eligible deposits are protected by the Financial Services Compensation Scheme (FSCS), the UK's deposit protection scheme. The FSCS deposit protection limit rose to £120,000 per eligible person, per authorised firm, on 1 December 2025. That means eligible deposits up to £120,000 are protected if the bank were to fail. Joint accounts are protected up to £120,000 per eligible person, so £240,000 for two holders. Temporary high balances, such as the proceeds of a house sale, can attract additional protection of up to £1.4 million for six months.
It is worth noting that a sale is not a failure. The FSCS only pays out if a bank actually fails, and Metro Bank is not failing: it is profitable, it has reaffirmed its guidance, and it is exploring a sale from a position of strength. The FSCS protection is a safety net in the background, not something customers need to claim because of this announcement. If a customer holds more than £120,000 with one banking licence, the amount above the limit would not be covered, and that is true at every UK bank, not only Metro Bank.
Customers should also beware of scams. Announcements about a bank being sold are routinely used by fraudsters, who send texts and emails pretending to be the bank and asking customers to move money to a "safe account" or to confirm security details. Metro Bank will not ask customers to move money because of the sale process, and customers should never act on such a message. Anyone who receives one should contact the bank through the number on the back of their card.
What about mortgages, loans and business accounts?
A mortgage is money the customer owes the bank, not money the bank holds for them, so a change of ownership does not change the mortgage. The borrower keeps paying the same amount, on the same terms, to whoever owns the loan. The same applies to personal loans and credit cards: the balance, the interest rate and the repayment terms stay as they are unless the contract itself allows a change, and any change would have to be notified in advance.
Business customers are in the same position. Metro Bank has built a significant business current account book, and commercial lending is one of the areas the board highlights as a strength. Business accounts, overdrafts and loans would transfer with the company in a sale, and business deposits are also eligible for FSCS protection, generally up to £120,000 per firm, subject to the scheme's eligibility rules for companies.
What should Metro Bank customers do now?
In short: nothing, unless they were already planning to change banks. There is no need to move money, close an account or withdraw cash because of this announcement, and doing so in a panic would achieve nothing: deposits are protected, accounts are operating normally, and no sale has been agreed. Customers who hold more than the FSCS limit may wish to review how their savings are spread, as they would at any bank, but that is a general point of good practice rather than a response to this news.
The sensible steps are to keep an eye on announcements from the bank itself, to be alert for scam messages trading on the news, and to remember that the process may end with no sale at all. The board has been explicit that there is no certainty an offer will be made, and it can end the process at any time. If a firm offer does emerge, it will be announced through the regulatory news service, and the Daily Byte will report what it means for customers at that point.
| Fact | Detail |
|---|---|
| Announcement | Formal sale process and strategic review, 12 November 2026 |
| Adviser | Morgan Stanley, lead financial adviser |
| Bidder | None named; no active discussions; no offer certain |
| Branches | 78 across England and Wales |
| Customers | Around 2.7 million |
| Half-year profit | £61 million pre-tax, six months to 30 June 2026, up 41% |
| FSCS deposit limit | £120,000 per eligible person, per authorised firm |
Frequently asked questions
Is Metro Bank closing down? No. It has launched a formal sale process, which is an invitation to potential buyers, not a closure. Its branches remain open and its accounts operate normally.
Is my money safe in Metro Bank? Eligible deposits are protected by the FSCS up to £120,000 per person, per authorised firm. The bank is profitable and is exploring a sale from a position of strength, not because it is failing.
Will my account number or sort code change? No change has been announced, and a change of ownership would not normally change account numbers or sort codes. Any future change would be communicated well in advance.
Should I move my money out of Metro Bank? There is no need to do so because of this announcement. Customers who hold more than the FSCS limit may wish to review their savings as a matter of general good practice.
When will we know if Metro Bank is sold? There is no timetable. The Takeover Panel has waived the usual 28-day deadline for bidders in the process, so it could take some time. Any firm offer would be announced through the regulatory news service.
Sources: LeapRate, The Sun, Messenger Newspapers, Consumer Protection UK