Mining giants lose $712bn as copper miners slump
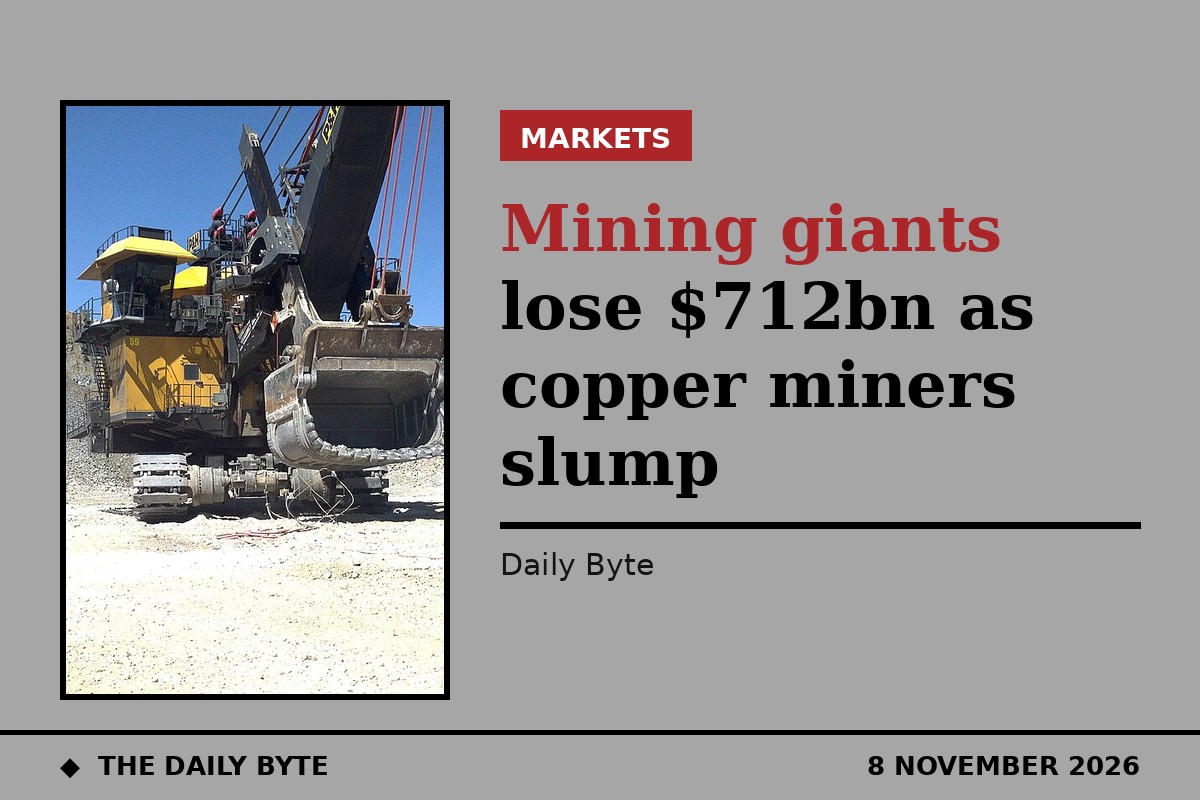
The world's 50 most valuable mining companies have lost $712 billion since February, wiping out more than a quarter of their value as investors pulled back from the sector. The MINING.COM TOP 50 ranking fell 26 per cent from its record $2.75 trillion at the end of February, with October alone taking $226 billion off the group, a 10 per cent decline on top of September's $264 billion loss, according to MINING.COM.
The slide is striking because metal prices themselves have held up far better than the shares. Gold ended October at $3,884 an ounce, down 6.6 per cent in its worst October since 2008, and the sixteen gold miners in the ranking gave up $55 billion, or 9.9 per cent. Silver had its worst month of the year, falling 18.2 per cent to $49.39. Copper barely moved, ending October at $6.47 a pound, only 1.4 per cent lower and still up 15 per cent for the year.
Yet the eleven copper producers in the ranking lost $69 billion in October, a 13.3 per cent fall and the largest of any sector in dollar terms. Antofagasta fell 16.1 per cent after a weaker 2027 production outlook and higher cost guidance, BHP missed quarterly copper estimates after a fatal accident and weather stoppages at Escondida, the world's largest copper mine, and Southern Copper lost 12.4 per cent, or $21 billion, in a month.
The sell-off matters in London, where miners including Antofagasta, Anglo American, Glencore and Rio Tinto are heavyweights in the FTSE 100. Kamoa Capital's weekly wrap notes the same pattern, with copper trading around $14,251 a tonne on the London Metal Exchange early in the week even as producers' shares fell. Analysts link the retreat to higher US interest-rate expectations, Middle East-driven oil gains and a rout in technology shares forcing funds to cut risk, rather than to the price of the metals in the ground.