What is the UK carbon border tax? CBAM explained
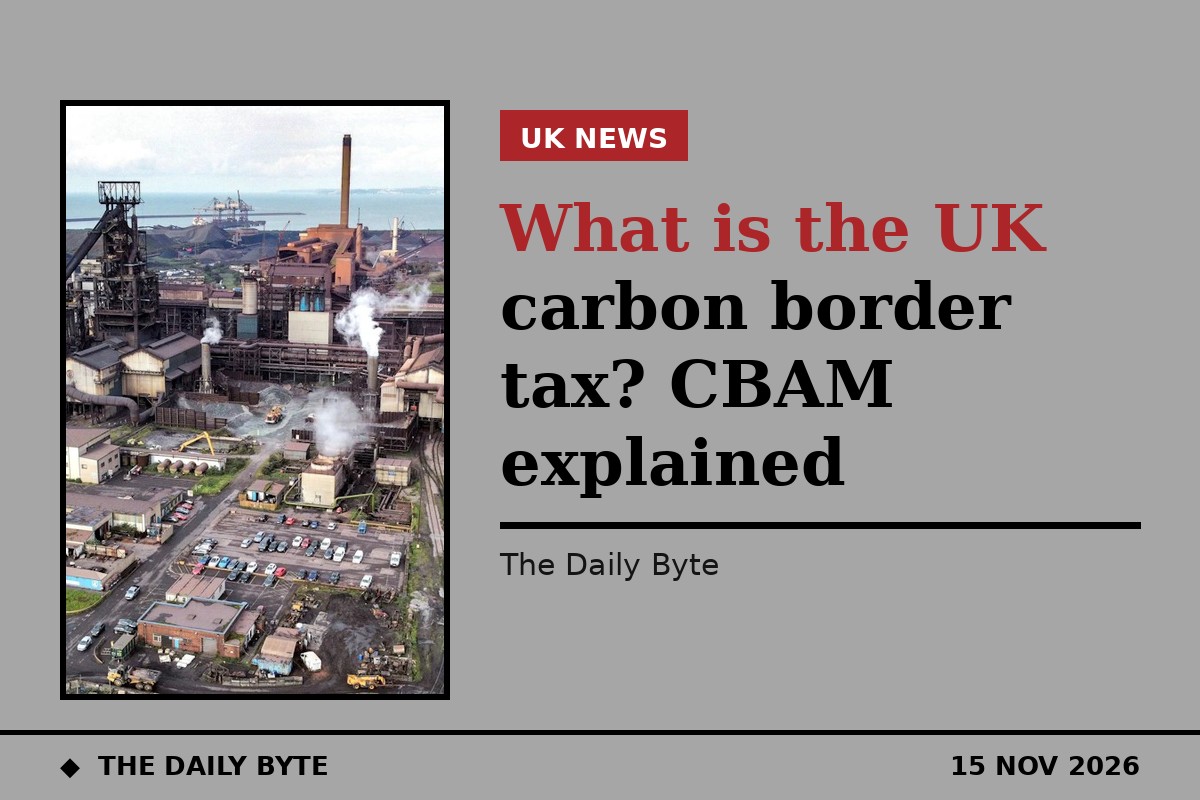
The UK carbon border tax — known as the Carbon Border Adjustment Mechanism, or CBAM — starts on 1 January 2027. From that date, importers of certain carbon-intensive goods, including iron and steel, aluminium, cement, fertiliser and hydrogen, will face a charge based on the carbon emissions embodied in what they bring into the country. Registration with HMRC does not open until 1 January 2028, and the first return and payment are not due until 31 May 2028 — but the liability, and the duty to keep records, begin on day one.
CBAM is designed to stop decarbonisation simply pushing emissions overseas. UK producers of steel, cement and other heavy goods already pay a carbon price under the UK Emissions Trading Scheme (UK ETS). Without a border charge, a UK buyer could avoid that cost by importing the same goods from a country with no carbon price at all. CBAM puts a comparable carbon price on those imports, so the incentive to move production abroad — known as carbon leakage — is reduced.
What is UK CBAM?
UK CBAM is a tax, collected by HM Revenue & Customs, on the carbon emissions embodied in specified imported goods. It was created by Part 5 of the Finance Act 2026, and the detailed rules sit in secondary legislation, including the Carbon Border Adjustment Mechanism (Emissions and Verification) Regulations 2026, which were made on 8 September 2026 and take effect on 1 January 2027.
The charge works in three steps. First, the importer works out the emissions embodied in the goods, in tonnes of carbon dioxide equivalent (CO2e). Second, HMRC sets a CBAM rate for each sector every quarter, linked to the UK ETS price. Third, the importer multiplies the emissions by the rate, and subtracts any relief for a carbon price already paid on those emissions overseas. The result is the CBAM due.
It applies across the whole of the UK, including Northern Ireland, and to imports of in-scope goods from 1 January 2027 onwards. Imports before that date do not count. The person liable is the importer — the person treated as the importer under the rules — not automatically the freight forwarder, customs agent or supplier named in the commercial paperwork.
Which goods are covered?
UK CBAM covers five sectors: aluminium, cement, fertiliser, hydrogen, and iron and steel. Only goods falling within specified commodity codes are in scope, so whether a particular shipment is caught depends on its eight-digit Combined Nomenclature code, not just on what the product is called. HMRC has published default emissions values for 570 commodity codes, and for iron and steel alone there are 478 codes, with default values ranging from 0.494 to 9.121 tonnes of CO2e per tonne of product.
| Sector | Illustrative CBAM rate (per tonne of CO2e) |
|---|---|
| Iron and steel | £9.69 |
| Aluminium | £9.79 |
| Cement | £8.78 |
| Fertiliser | £1.45 |
| Hydrogen | £9.24 |
The rates in the table are HMRC’s illustrative rates, published on 16 October 2026. They are worked out from the average UK ETS auction price for July to September 2026, which was £58.15 per tonne of CO2e, adjusted for the share of emissions that still benefit from free UK ETS allowances. They are illustrative only: HMRC says plainly that they create no liability and are not forecasts. The binding rates for January to March 2027 will be published before the end of 2026, and new rates will follow each quarter.
Who has to register?
An importer must register for CBAM once the value of its imports of covered goods reaches £50,000. There are two tests. Under the forward-looking test, you must register if you expect to import covered goods worth £50,000 or more within the next 30 days. Under the backward-looking test, on the first day of each month you check whether your imports of covered goods over the previous 12 months have reached £50,000.
Registration itself is where the timetable catches people out. The registration service opens on 1 January 2028 — a full year after the tax starts. Anyone who becomes liable during 2027 must register by 31 January 2028. The first accounting period covers the whole of calendar year 2027, and the first return and payment are due by 31 May 2028. From 2028, accounting periods become quarterly: the first quarterly return, for January to March 2028, is due by 31 July 2028.
That gap does not defer the tax. An importer that crosses the threshold during 2027 is liable from its liability date in 2027 and must register and account for the tax once the service is available. The government’s costing projects the tax will raise £30 million in 2026–27, rising to £180 million a year by 2028–29, from an estimated 10,000 affected businesses.
The 2027 records trap
The most consequential part of the timetable is the one that looks like a grace period but is not. HMRC updated its CBAM guidance on 10 November 2026 to confirm that importers of in-scope goods must keep records from 1 January 2027, even though registration does not open until a year later. Records are required even where an importer is not liable for the tax, and even for CBAM goods that the importer believes are exempt.
For each CBAM good, the records must include the eight-digit commodity code and description, the date the goods passed the tax point, the value, the net mass in kilograms excluding packaging, and evidence supporting any exemption claimed. Records must generally be kept in written or electronic form for six years from the later of their creation date or the end of the relevant accounting period.
The penalties underline why the records matter. A fixed £500 penalty, plus £40 for every additional day, can apply for failing to notify HMRC of a change in registration details, and a flat £500 penalty applies for failing to keep required records. Fraudulent evasion of CBAM carries up to 14 years’ imprisonment on indictment. An importer that waits until registration opens in 2028 to start gathering evidence will have nothing to file with — and no way to reconstruct a year of shipments reliably.
What if the emissions data is missing?
Wherever possible, HMRC wants actual verified emissions data from the overseas plant that made the goods. But many importers will not be able to get it, at least at first. For that situation, HMRC has published default emissions values that stand in for missing data. The defaults are based on EU data, calculated to reflect the same system boundaries as the UK scheme, with a 10 per cent markup applied in all sectors except fertiliser, where no markup is applied. The government’s stated principle is that using a default should give a liable person no advantage over measuring actual embodied emissions.
The default values will be in force from 1 January 2027 to 31 December 2028. From 2029, the UK will move to country-specific default values, with one default per CBAM good per country. There is a catch importers need to understand early: a return completed using default values cannot later be amended to use actual emissions data. The choice made for 2027 is, in effect, final — which is why HMRC and advisers have been urging importers to start talking to their suppliers about verified data now, before the first accounting period begins.
Carbon price relief
If the emissions embodied in imported goods have already been subject to a carbon price in the country where they were produced, the importer may be able to claim carbon price relief, reducing the CBAM due. HMRC published guidance on claiming the relief on 16 July 2026.
To qualify, the overseas carbon pricing scheme must be a qualifying scheme, and the installation that made the goods — or another entity in the supply chain — must provide a carbon pricing verification form completed by an independent verifier who meets the accreditation requirements. HMRC sets out a four-step process: check the scheme qualifies, get the verification form, gather the publicly available data needed (including headline carbon prices from the previous calendar quarter), and then work out the relief for each individual CBAM good, converting any foreign currency figures into sterling before submitting the claim as part of the CBAM return.
How is UK CBAM different from the EU version?
The UK scheme is deliberately not a copy of the European Union’s CBAM. The EU system requires importers to buy certificates; the UK version is a tax collected by HMRC, with a tax return instead of certificates. The UK covers five sectors instead of the EU’s six, uses a £50,000 value threshold for registration, and currently exempts no country of origin.
One question hanging over both schemes is whether the UK and EU emissions trading systems will be linked. The Prime Minister told the Commons on 12 October 2026 that a summit in Brussels on 20 November would discuss an emissions trading deal. No linking agreement text has been published, and neither government has given a date for a link to take effect, so importers should plan on the basis of the UK scheme as it stands.
What should importers do now?
With the start date weeks away, the practical checklist is short but unforgiving. Check which commodity codes you import against HMRC’s list of goods in scope. Work out whether you cross the £50,000 threshold, and from when. Put record-keeping in place from 1 January 2027, even if you expect to fall below the threshold. Ask overseas suppliers for verified emissions data, and decide whether you will use actual data or HMRC’s defaults — remembering that a default-based return cannot be amended later. And watch for the binding first-quarter rates, which HMRC will publish before the end of 2026.
For businesses that import steel, aluminium, cement, fertiliser or hydrogen, the message of the last two months of HMRC publications is consistent: the tax starts in January, the paperwork starts in January, and the registration system arriving a year later is not a year’s grace.
Frequently asked questions
When does UK CBAM start? 1 January 2027. It applies to in-scope goods imported into the UK on or after that date, across the whole of the UK including Northern Ireland.
Do I need to register straight away? No — registration opens on 1 January 2028. But if you become liable during 2027 you must register by 31 January 2028, and you must keep records from 1 January 2027.
When is the first payment due? The first return and payment, covering calendar year 2027, are due by 31 May 2028. Returns become quarterly from 2028.
Which goods are covered? Specified goods in five sectors — aluminium, cement, fertiliser, hydrogen, and iron and steel — identified by their commodity codes. The importer, not the supplier or freight forwarder, is liable.
What are the CBAM rates? HMRC’s illustrative rates are £9.69 per tonne of CO2e for iron and steel, £9.79 for aluminium, £8.78 for cement, £1.45 for fertiliser and £9.24 for hydrogen. These are illustrative only; the binding rates for January to March 2027 will be published before the end of 2026.
Sources: HM Revenue & Customs (GOV.UK) and KPMG.